Lola Kay
CEO & Business Credit and Financing Expert
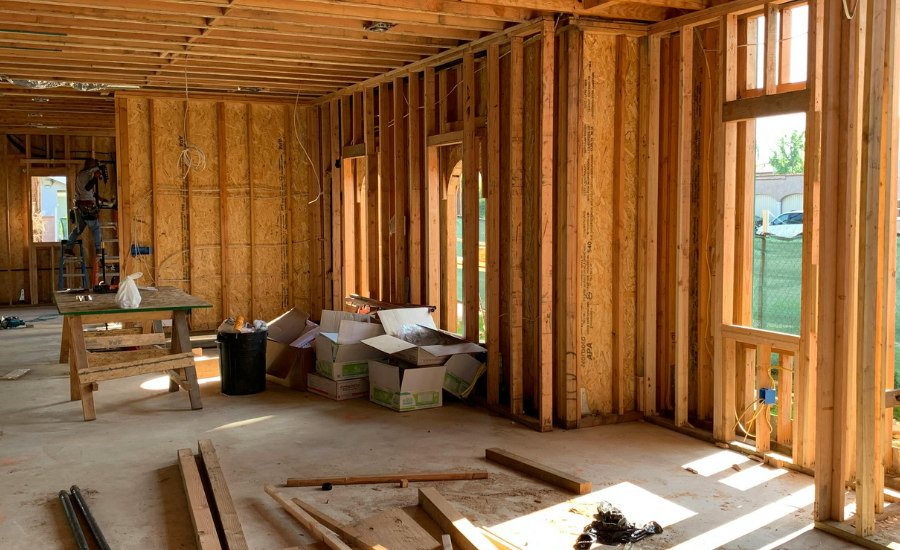
Okay, so you’re running a construction business and the jobs are coming in, but you’re still lying awake wondering how you’re going to make payroll because a customer hasn’t paid yet. The common construction cash flow problem – the money is owed to you, but that doesn’t help much when your crew needs to be paid on Friday.
This is a common challenge in construction. You’re paying for labor, materials, and subcontractors while waiting for payments on work you’ve already completed. So, what can you do about it?
What you can do
Plan ahead. Look at what’s coming in and what’s going out over the next 4-13 weeks. Include payroll, materials, subcontractors, and other bills. Be realistic about when customers will actually pay, not just when their invoices are due.
Stay on top of billing. Send progress invoices on time and follow up when payments are late. The longer an invoice sits unpaid, the longer you’re waiting for money you’ve already earned.
Have a plan for the gaps. If you know a large payment won’t arrive before payroll is due, don’t wait until the last minute to figure out what to do. Building a cash reserve, negotiating payment terms with suppliers, or exploring financing may help, depending on your situation.
You can have profitable projects and work lined up and still run into cash flow problems. Knowing when you’ll get paid and when your bills are due makes a real difference.
Financing options worth understanding before you’re in a bind
A Business Line of Credit is often a great option for recurring cash flow gaps. You draw what you need, repay it as money comes in, and access the available credit again. Depending on the lender and your qualifications, it may be unsecured or secured by accounts receivable. These are usually the first choice for construction owners.
Working Capital financing can cover payroll, materials, and operating expenses while you wait for project payments or take on new work. Non-bank lenders focus heavily on business revenue rather than requiring profitability, which makes it the most common product.
Accounts Receivable financing can help you access funds tied up in eligible unpaid invoices instead of waiting for customers to pay. Invoice factoring is another option, where invoices are sold to a financing company. The costs and terms vary, so understand exactly what you’re agreeing to.
Equipment Financing can help you purchase or replace trucks, trailers, excavators, skid steers, and other job-site equipment that is necessary to run your business without paying the full cost upfront and draining your working capital.
And then the MCA (merchant cash advance). Proceed with caution. Understand the total cost, payment frequency, and how repayments will affect your daily cash flow. Frequent withdrawals can make a tight situation even tighter.
Find out what you qualify for before you need it.
Pick the option that fits the gap
Not every construction cash flow problem needs the same fix. If the gaps keep coming back, a line of credit usually makes the most sense because you can reuse it. If you need money to cover a specific stretch while you wait on a big payment, working capital or receivables financing may fit better. Equipment financing is for when the truck or excavator is the issue, not payroll. And whatever you’re offered, ask for the total cost in dollars, not just a rate or a factor, so you can compare options side by side.
The best time to line up financing is before you need it. Lenders look at your revenue, time in business, and credit, and an application you submit while things are steady is a lot easier than one you submit while payroll is due in two days.